
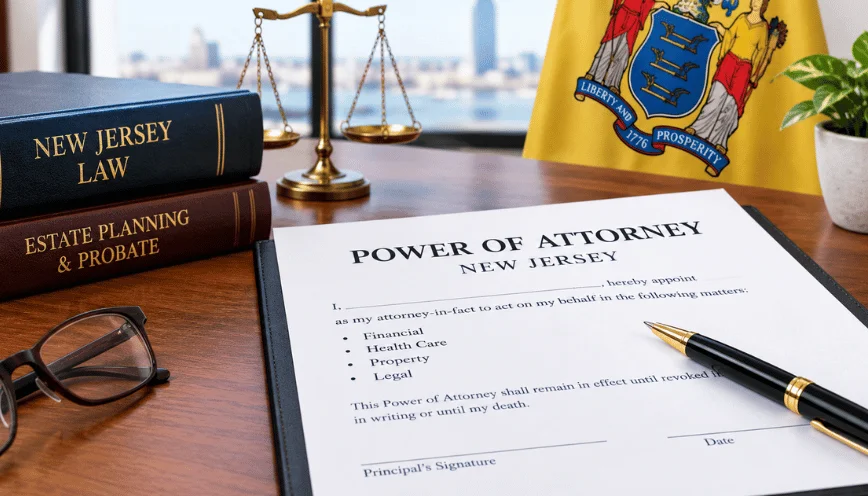
A power of attorney in NJ lets you authorize another person to handle specified matters for you. The document can cover finances, property, banking, taxes, or other listed responsibilities. New Jersey law sets important rules for signing, durability, agent duties, and ending that authority.
Quick answer: A New Jersey financial POA must be written, signed, and properly acknowledged. A durable document needs language showing authority survives later incapacity. Your agent must act within the granted powers and for your benefit, while health-care decisions require a separate health-care directive.
New Jersey POA Quick Facts
| Question | New Jersey rule |
|---|---|
| Governing law | Revised Durable Power of Attorney Act, N.J.S.A. 46:2B-8.1 et seq. |
| Must it be written? | Yes. |
| Signing requirement | Signed and properly acknowledged |
| Durable by default? | No |
| Can it become effective after incapacity? | Yes, if drafted that way |
| Agent’s legal role | Fiduciary |
| Does financial authority cover health care? | No |
| Can the principal revoke it? | Yes, using legally recognized methods |
| Does it continue after death? | No |
What Does a New Jersey Power of Attorney Do?
A POA names a principal and an agent, traditionally called an attorney-in-fact. The principal gives that agent authority through a written legal document. The scope depends on the powers stated in the document.
Financial authority can cover banking, real estate, investments, taxes, benefits, or business matters. A narrow document might authorize only one transaction. A broader document may allow an agent to manage several categories of property.
This planning tool can become especially important during illness or declining capacity. Families considering wider incapacity planning may also benefit from Lawflowa’s elder law attorney guide. That guide discusses estate planning, guardianship, health directives, and related concerns.
1. A New Jersey Financial POA Must Meet Formal Signing Rules

New Jersey requires the document to be in writing. N.J.S.A. 46:2B-8.9 also requires it to be duly signed and acknowledged. The acknowledgment follows the state’s rules for formally acknowledged instruments.
In practice, that commonly means signing with a notary or another authorized officer handling the acknowledgment. The statute does not impose a separate two-witness requirement for this financial document. Different rules can apply to other estate-planning instruments.
The signing ceremony matters because banks and other institutions may examine the document closely. A poorly executed document can create delays when the agent needs authority most. Using a New Jersey-specific form or legal review can reduce that risk.
2. Durability Is Not Automatic in New Jersey
A standard financial POA does not automatically remain effective after later incapacity. New Jersey requires language showing that continued authority was intended. N.J.S.A. 46:2B-8.2 provides examples of acceptable durability wording.
One approach states that authority will not be affected by later disability or incapacity. Another states that authority begins when disability or incapacity occurs. Similar wording can also establish the required intent.
This distinction matters because incapacity planning is a common reason for creating the document. A nondurable document may fail when the principal can no longer manage personal affairs. That result can force relatives to explore court-supervised alternatives.
3. Immediate and Springing Authority Work Differently
An immediate document allows the named agent to use granted powers without waiting for later incapacity. This can make routine assistance and emergency financial management easier. It also demands strong confidence in the chosen agent.
A springing document delays authority until a stated condition occurs. That condition often involves disability or incapacity under terms written into the document. The drafting should explain how the triggering condition will be established.
Banks can request satisfactory proof when authority depends on the principal’s disability. That verification can add time during an urgent situation. Families should weigh convenience against the control offered by delayed authority.
How to Create a Power of Attorney in NJ That Works
A reliable document starts with careful decisions rather than a generic signature page. The principal should define who may act and exactly what that person may do. The document should then satisfy New Jersey’s execution rules.
A practical process includes:
- Decide which financial or property powers the agent needs.
- Choose an agent whose judgment and honesty you trust.
- Name a successor agent when appropriate.
- Decide whether authority starts immediately or after a trigger.
- Add clear durability wording when continued authority is intended.
- Address specialized powers, including gifting, when necessary.
- Sign and acknowledge the document correctly.
- Give usable copies to institutions that may need them.
Broad authority should not be granted casually. The person selected may gain substantial control over accounts and property. Complex assets, family conflict, or Medicaid planning can justify attorney review.
For planning involving aging, benefits, or long-term care, see Lawflowa’s elder law lawyer guide. Those issues can interact with financial authority in important ways. Coordinating the documents can prevent conflicting instructions later.
4. Choose the Agent Carefully
An agent may receive access to bank accounts, investments, real estate, and other valuable property. Trustworthiness should therefore matter more than convenience alone. Availability and financial judgment also deserve consideration.
New Jersey law treats the agent as a fiduciary. The agent must stay within the powers granted and act for the principal’s benefit. Financial records should also be accurate and available when an accounting is legally requested.
Naming a backup can prevent the arrangement from failing when the first agent cannot serve. Co-agents are possible, but they can complicate decisions and signatures. Clear drafting should explain how multiple agents are expected to act.
5. Some Powers Need Especially Clear Language
A broad phrase does not always solve every future financial problem. Some transactions deserve specific drafting because they can change the principal’s property or estate plan. Gifting is a major example.
New Jersey restricts an agent’s ability to make gifts of the principal’s property without appropriate authority. This rule helps protect owners against unauthorized transfers. Estate or Medicaid strategies involving gifts require careful legal review.
Real estate, trusts, business interests, and tax matters can also need detailed provisions. Generic online documents may not reflect the principal’s actual goals. Precision becomes more important as the assets or planning objectives become complicated.
6. Financial POA and Health-Care Authority Are Different
A financial agent does not automatically receive medical decision-making power. New Jersey handles health-care authority through advance directives. The state calls the appointment document a proxy directive.
A proxy directive names a healthcare representative for periods when the patient cannot make medical decisions. New Jersey also recognizes an instruction directive, commonly called a living will. A person can use either type or both.
According to the New Jersey Department of Health, the proxy takes effect after the required incapacity determination. The representative then makes medical choices within the document’s limits. Keeping financial and medical documents distinct prevents confusion.
7. A POA Can Be Revoked, but Notice Matters
New Jersey provides several methods for revoking financial authority. The principal can destroy all executed originals or use a properly acknowledged written revocation. Written revocation can also be delivered to the agent.
Signing a newer document does not automatically cancel an older one unless the documents provide for that result. This can create serious confusion when several versions remain in circulation. Revocation planning should therefore address both paperwork and notice.
Banks and other third parties should receive notice when an agent’s authority ends. Leaving an outdated copy with an institution can create avoidable problems. Keep records showing where active and revoked copies were distributed.
What Happens When a Bank Receives the Document?
New Jersey has specific rules addressing financial institutions and qualifying POAs. Banks generally may rely on a document that conforms to applicable requirements. They can refuse reliance in circumstances identified by law.
It can help to ask major financial institutions about their review procedures after signing. That does not replace legal validity requirements. It can identify practical documentation issues while the principal can still address them.
Common New Jersey POA Mistakes
Many failures come from drafting or administration rather than the basic concept. These problems often surface after illness, incapacity, or family disagreement. By then, correcting the document may be difficult.
Common mistakes include:
- using a generic form without New Jersey durability language;
- giving an agent powers the principal never intended;
- failing to address gifts or unusual transactions clearly;
- confusing financial authority with a medical proxy;
- choosing an unreliable or unavailable agent;
- failing to name a successor;
- leaving revoked copies with banks or family members;
- Assuming a new document automatically cancels every older version.
Disputes over authority can become part of wider estate conflicts. Lawflowa’s probate litigation lawyer guide explains fiduciary disputes, capacity claims, and related estate conflicts. Good documentation now can reduce uncertainty later.
When Should You Speak With a New Jersey Attorney?
Simple circumstances do not always require complicated planning. Yet legal review becomes more useful when the document controls significant assets. The same applies when family relationships or future benefits create unusual risks.
Consider professional guidance when you own a business or substantial real estate. Legal advice can also help with gifts, trusts, Medicaid planning, or contested family relationships. Cross-state property can add another layer of complexity.
An attorney can coordinate financial authority with a will, trust, and health-care directives. That coordination helps each document perform its intended job. It also reduces conflicting instructions between different parts of the estate plan.
Frequently Asked Questions
Does a power of attorney in NJ need to be notarized?
New Jersey requires a financial POA to be signed and formally acknowledged. A notary public commonly performs that acknowledgment. N.J.S.A. 46:2B-8.9 sets the underlying formality requirement.
Does a New Jersey POA remain valid after incapacity?
Only when the document contains language establishing durability. New Jersey does not automatically treat every POA as durable. The wording should clearly show the principal’s intent for authority to survive or begin upon incapacity.
Can an agent give away the principal’s money?
Not simply because the document grants broad financial authority. New Jersey places specific restrictions on gifts of the principal’s property. Plans involving gifting should use carefully drafted authority.
Does the agent own the principal’s property?
No, the agent receives authority to act within the document’s limits. New Jersey imposes fiduciary duties requiring conduct for the principal’s benefit. The agent can also be required to account for financial transactions.
Does financial authority continue after the principal dies?
No, a POA is a lifetime authority arrangement rather than authority to administer a deceased person’s estate. After death, an executor or administrator generally handles estate matters. The relevant authority comes from estate administration law, not the former agent’s document.
The Bottom Line
A New Jersey POA can protect financial continuity during travel, illness, aging, or incapacity. Its usefulness depends on correct execution, suitable powers, and a trustworthy agent. Durability language is especially important when incapacity planning is the goal.
Review the document whenever your relationships, assets, or planning goals change. Confirm that trusted people know where current copies are stored. For complex circumstances, have a New Jersey attorney review the document before you rely on it.